
- U.S. GAAP and IFRS require the functional currency approach for reporting the financial results of a foreign subsidiary in the parent company’s presentation currency.
- The functional currency method consists of three steps:
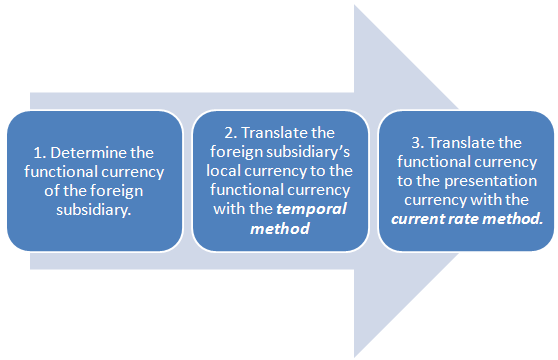 NOTE: Step 2 is only necessary in instances when the local currency is different from the functional currency.
- If Local Currency = Functional Currency ≠ Presentation Currency, then translate from Functional Currency to Reporting/Presentation Currency with the Current Rate Method.
- If Local Currency ≠ Functional Currency = Reporting Currency, then translate the Local Currency to the Functional Currency with the Temporal Method.