Finance Train LogoFinance Train
Learning LibraryTemplatesBlog
Data Science Bundle
Finance TrainFinance Train
Learning LibraryTemplatesBlog
Data Science Bundle
Securities & Markets

Calculate the Value of a Coupon Paying Bond

October 14, 2013
1 min read

The value of a coupon paying bond is calculated by discounting the future payments (coupon and principal) by an appropriate discount rate.

Suppose you have a bond with a $1,000 face value that matures 1 year from today. The coupon rate is 12% and the bond makes semi-annual coupon payments of $60. The bond yield is 13%. The cash flows from the bond are depicted below:
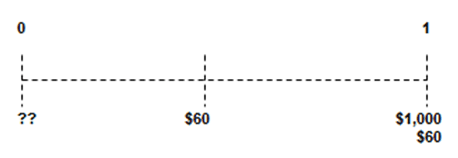
bv1
bv1
 The bond characteristics are summarized below:

  • Par Value =     $1,000
  • Yield        =      13% annual (13/2 =6.5% semi-annual)
  • Coupon   =      12% with semi-annual payment of $60
  • Maturity   =      1 year

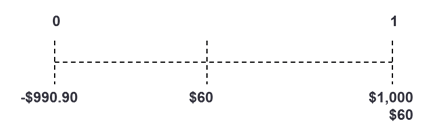
The value of the bond is calculated as follows:
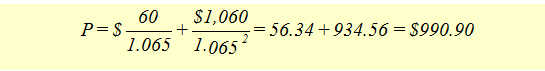
bv2
bv2

Note that the coupon is paid semi-annually, i.e., $60 per 6 months. The discounting is also done semi-annually.
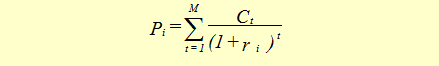
bv3
bv3
 The general bond pricing formula for all bonds can be stated as:


bv4
bv4

Where:

  • Pi =  the price of the bond i
  • Ct = cash flow from the bond i at time t
  • ri = the annualized yield to maturity on bond i
  • M = the time in years until the bond matures

Learning Library

Practical resources on data science, machine learning, and AI for finance professionals.

Browse Library
Mini Roadmap - Data Science for Finance
Free Download

Mini Roadmap: Data Science for Finance

A step-by-step guide covering Python, SQL, analytics, and finance applications.

Finance Train

Learn data science and AI skills for finance through practical courses and tutorials.

Learn

  • Learning Library
  • Course Directory
  • Blog

Resources

  • Templates & Downloads
  • Tools
  • Tables
  • Calculators

Company

  • About
  • Contact
  • Privacy
  • Terms

© 2026 Finance Train. All rights reserved.